Hurricane and Flood Considerations When Buying on Isle of Palms
Hurricane and Flood Considerations When Buying on Isle of Palms
By Leah Beaulieu & BJ Rodgers, Coast2Coast Properties
Updated September 2026 | Charleston, South Carolina
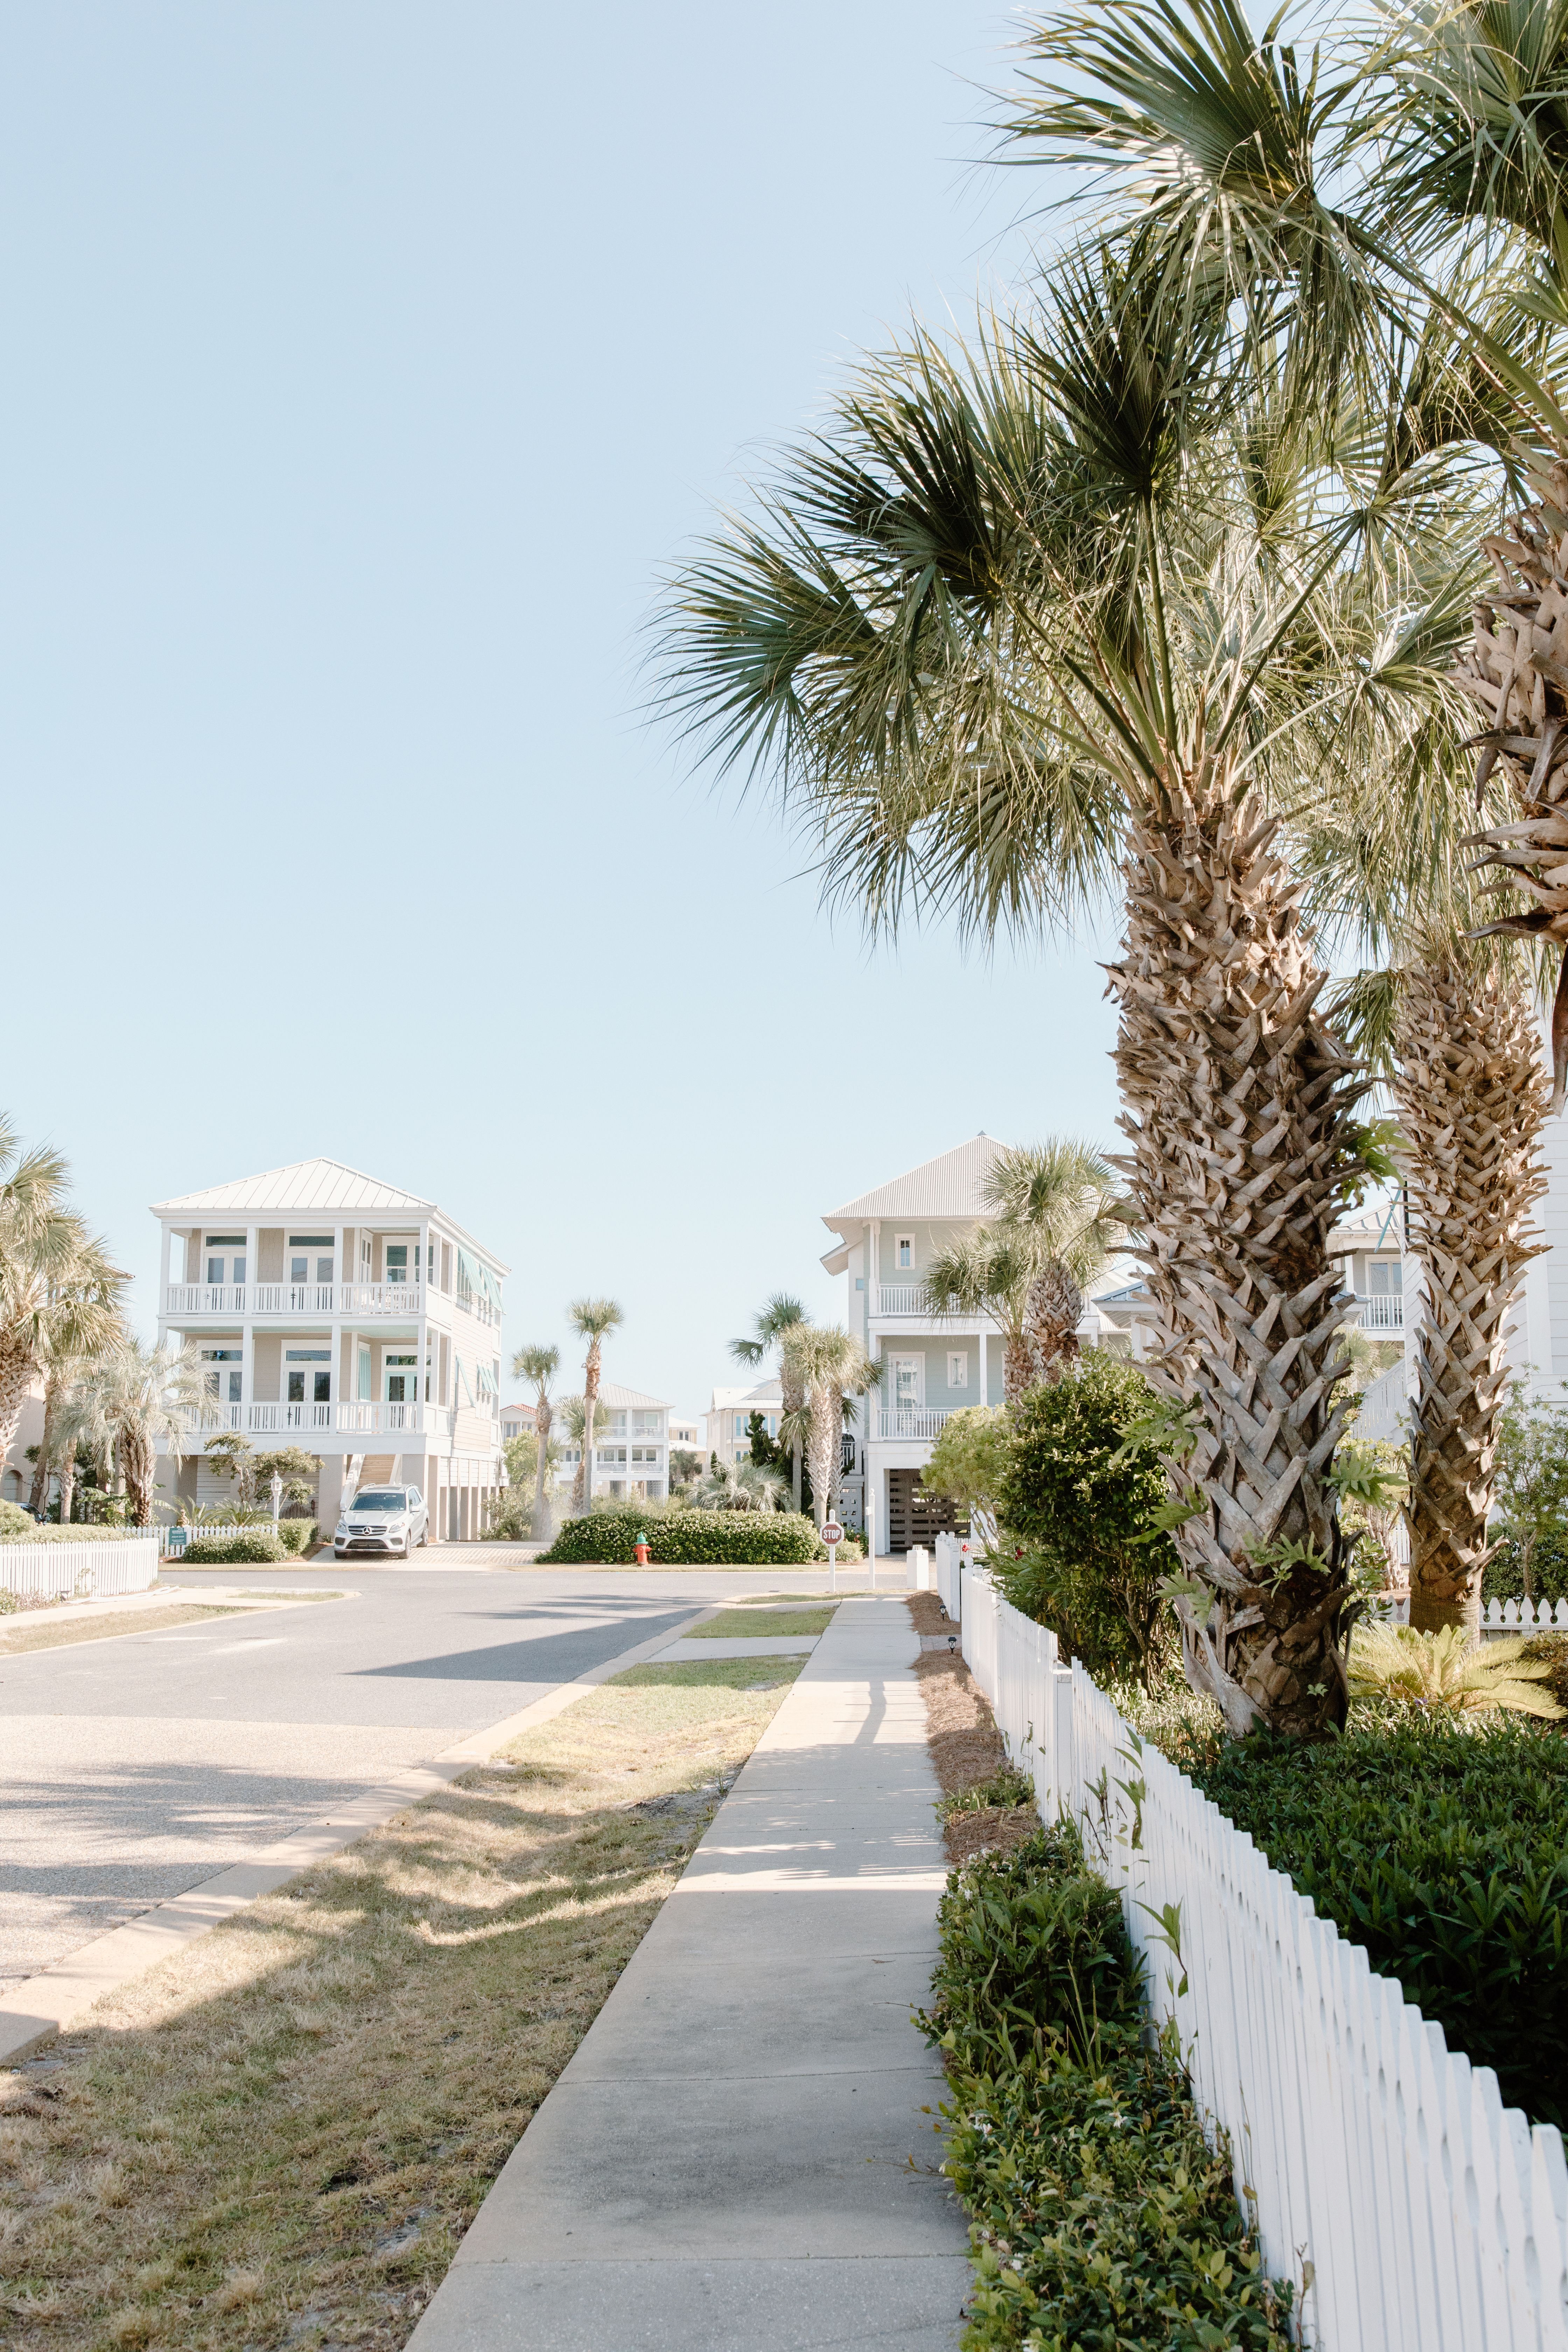
Isle of Palms 29451 is Charleston's larger barrier island—more developed, more accessible, and home to a broader range of luxury properties than its smaller neighbor, Sullivan's Island. Median home prices on Isle of Palms range from $1.2M–$4M for oceanfront homes and $600K–$2M for interior properties, making it an attractive entry point for luxury buyers seeking barrier-island living without Sullivan's Island's ultra-premium price tags.
But Isle of Palms carries its own hurricane reality. The island faces identical storm surge exposure to Sullivan's Island (98% flood risk), yet maintains better evacuation infrastructure and somewhat lower insurance costs. This guide walks through Isle of Palms' specific hurricane and flood considerations—what the island's wider appeal actually costs in terms of weather risk, insurance premiums, and post-storm recovery timelines.
The Short Answer
- Isle of Palms is a barrier island with 98% flood risk and direct Atlantic hurricane exposure—nearly identical to Sullivan's Island (99% risk)—yet maintains better evacuation logistics thanks to multiple island access routes.
- The Isle of Palms connector (SC 517) provides the primary evacuation route, feeding into US 17 or I-526, offering evacuees destination choice—more flexibility than Sullivan's Island's single SC 703 route.
- Annual windstorm insurance typically runs $4,000–$12,000 depending on elevation and oceanfront exposure—less than Sullivan's Island but substantially more than inland Charleston neighborhoods.
- Flood insurance is mandatory and averages $1,183–$4,000 annually depending on flood zone (AE, VE, or X) and elevation. Isle of Palms' Community Rating System (CRS) Class 5 status provides up to 25% discount on NFIP flood insurance.
- Evacuation is faster and more flexible than Sullivan's Island—multiple routes and island access points typically clear the island in 3–6 hours for serious hurricanes, compared to 8–14 hours for Sullivan's Island.
- Hurricane Hugo (1989) inundated both islands with 13-foot storm surge—a reminder that both islands face severe hurricane risk regardless of difference in size or development patterns.
- Post-storm recovery typically takes 5–10 days for power and water restoration, with barrier-island prioritization after mainland recovery is complete.
Understanding Isle of Palms' Unique Geography & Risk Profile
Isle of Palms spans roughly 7 miles—nearly twice Sullivan's Island's length—with neighborhoods ranging from beachfront oceanfront ($2M–$4M+) to tree-lined interior streets ($600K–$1.5M). The island's size creates some advantages over Sullivan's Island, but the geographic risk profile remains nearly identical.
Flood Risk Comparison: Isle of Palms sits at 98% flood risk; Sullivan's Island at 99%. This one-percentage-point difference is statistically negligible—both islands are in the highest-risk category for Atlantic coastal properties.
Storm Surge Exposure: During Hurricane Hugo (1989), storm surge on both islands exceeded 13 feet above normal high tide. Oceanfront homes on both islands face identical wind and surge exposure. Interior homes on Isle of Palms sit slightly lower (better trees and windbreak coverage), but flooding still affects ground-level systems.
Evacuation Advantage: This is where Isle of Palms genuinely differs from Sullivan's Island. The Isle of Palms connector provides two primary evacuation destinations (US 17 north toward Myrtle Beach, or I-526 west toward Columbia), offering evacuees destination flexibility. Sullivan's Island has only SC 703 into I-526. Multiple routes allow Isle of Palms evacuations to clear faster (3–6 hours vs. 8–14 hours).
Flood Insurance & CRS Rating: Isle of Palms' Hidden Advantage
All Isle of Palms properties sit in FEMA flood zones—typically Zone AE (high-risk coastal) or Zone VE (coastal wave-hazard). This means flood insurance is mandatory for mortgaged properties, and premiums are substantial.
The CRS Class 5 Advantage
Isle of Palms maintains a FEMA Community Rating System (CRS) Class 5 rating, which qualifies property owners in the Special Flood Hazard Area for up to a 25% discount on National Flood Insurance Program (NFIP) premiums. This is a meaningful advantage.
Example: A Zone AE home with a base NFIP rate of $4,000/year receives a $1,000 discount (25%) thanks to CRS Class 5 status, reducing the premium to $3,000/year.
Sullivan's Island does not maintain as robust a CRS rating, so Isle of Palms buyers get a modest but real insurance advantage.
Typical Annual Flood Insurance Costs
- Zone X (outside special flood hazard area): $500–$1,000/year (if available)
- Zone AE (coastal, high-risk): $1,500–$3,000/year with CRS discount
- Zone VE (coastal wave-hazard): $2,500–$4,000+/year (higher premiums for surge-exposed properties)
For a $2M oceanfront Isle of Palms home in Zone VE, budget $3,000–$4,000/year for flood insurance alone. This is mandatory; there's no option to skip it.
Windstorm Insurance on Isle of Palms
Separate from flood insurance, windstorm coverage protects against hurricane winds and wind-borne debris:
- Interior homes ($800K–$1.5M): $2,500–$4,000/year windstorm
- Oceanfront homes ($2M–$3.5M): $5,000–$8,000/year windstorm
- Premium oceanfront ($3.5M+): $8,000–$12,000/year windstorm
Total annual insurance cost for a $2M oceanfront Isle of Palms home: $8,000–$12,000/year (windstorm + flood), with windstorm deductibles typically 1–2% of home value ($20,000–$40,000).
This is notably lower than Sullivan's Island ($12,000–$25,000/year) due to Isle of Palms' larger island size, multiple evacuation routes, and lower perceived-risk profile among insurers.
Evacuation Routes & Logistics: Isle of Palms' Advantage
During hurricane threats, Isle of Palms residents use the Isle of Palms connector (SC 517) as the primary evacuation route, feeding into either US 17 (north toward Myrtle Beach/North Carolina) or I-526/I-26 (west toward Columbia). This dual-route capability creates significant logistics advantages over Sullivan's Island's single SC 703 bottleneck.
Evacuation Timing
- Voluntary evacuation (Category 1–2 threat): 30–45 minutes clear time; most interior residents choose to stay
- Mandatory evacuation (Category 3+ threat): 3–6 hours to clear island vs. 8–14 hours for Sullivan's Island
- Peak evacuation (same day as Category 4+ landfall threat): 4–8 hours with congestion, still manageable
Evacuation Destinations
Many Isle of Palms residents evacuate north (US 17 toward Myrtle Beach, Wilmington, Virginia) rather than west (I-26 toward Columbia). This distribution reduces the singular-bottleneck problem that Sullivan's Island faces. Hotel availability is better, traffic is more dispersed, and return to the island after the storm is typically 5–7 days vs. 7–10 days for Sullivan's Island.
Elevation Requirements & Construction Standards
Like Sullivan's Island, most Isle of Palms homes must be elevated 10–16+ feet above base flood elevation (BFE), depending on location. This is a building code requirement for barrier-island coastal properties.
Oceanfront homes sit on pilings; mechanical systems (HVAC, electrical panels, water heaters) are elevated to prevent flood damage. Ground-level garages and storage are designed for flood inundation. These are standard practices, not unusual, and they increase construction costs 8–12% compared to inland homes.
A Realistic Example: Buying a $2M Oceanfront Home on Isle of Palms
You're purchasing a $2M oceanfront home on Isle of Palms, built in 2010, with impact windows, backup generator, and modern elevation. Here's the financial reality:
Insurance Costs
- Windstorm: $6,000–$8,000/year
- Flood (Zone VE with CRS 25% discount): $3,000–$4,000/year
- Total: $9,000–$12,000/year
- Windstorm deductible: $40,000 (2% of $2M)
- Flood deductible: $2,500–$5,000
Evacuation Planning
- Expect 1–2 mandatory evacuations per hurricane season on average
- Evacuation timing: 3–6 hours to clear island (vs. 8–14 for Sullivan's Island)
- Hotel/logistics: $2,000–$4,000 per evacuation
- Better route options (US 17 north or I-526 west) offer destination flexibility
Recovery After Hurricane
- Power restoration: 5–7 days (barrier islands lag mainland by 5+ days)
- Water service: 3–5 days
- Road access and emergency services: Usually maintained throughout (multiple routes allow re-entry faster than Sullivan's Island)
Annual Storm Prep
- Roof and gutter inspection: $500–$700
- Generator maintenance: $800–$1,000
- Window/shutter inspection: $300–$500
- Pilings and foundation inspection: $400–$600
- Total annual: $2,000–$2,800
Resale Considerations
- Oceanfront prestige commands 8–12% premium over comparable interior Isle of Palms homes
- Broader buyer pool than Sullivan's Island (more price-sensitive luxury buyers)
- Insurance costs impact buyer financing less than Sullivan's Island (lower premiums)
- Faster market recovery post-storm due to better evacuation logistics
Isle of Palms vs. Sullivan's Island: Direct Comparison
| Factor | Isle of Palms | Sullivan's Island |
|---|---|---|
| Flood Risk | 98% | 99% |
| Oceanfront Price Range | $1.5M–$4M | $5M–$15M+ |
| Interior Price Range | $600K–$1.5M | $2.5M–$3.5M |
| Annual Windstorm Insurance | $4K–$8K (interior), $6K–$12K (oceanfront) | $5K–$8K (interior), $12K–$25K+ (oceanfront) |
| Annual Flood Insurance | $1.2K–$4K (CRS discount available) | $2K–$4K (no CRS discount) |
| Evacuation Routes | 2–3 routes (I-526 or US 17) | 1 route (SC 703) |
| Evacuation Time | 3–6 hours | 8–14 hours |
| Hurricane Hugo (1989) Damage | 13-foot storm surge, severe | 13-foot storm surge, severe |
| Buyer Pool | Broad (moderate luxury) | Ultra-high-net-worth only |
| Post-Storm Recovery | 5–7 days power, multiple access | 7–10 days power, single access |
Bottom Line: Isle of Palms faces nearly identical flood and hurricane risk to Sullivan's Island but offers better evacuation logistics, lower insurance costs, and broader buyer appeal due to more accessible price points. For luxury buyers wanting barrier-island oceanfront access without Sullivan's Island's ultra-premium costs and evacuation constraints, Isle of Palms delivers a pragmatic alternative.
Mistakes Isle of Palms Buyers Make
Mistake 1: Assuming larger island = lower risk. Isle of Palms is 7 miles long vs. Sullivan's Island at 3 miles, but flood risk is virtually identical (98% vs. 99%). Size provides evacuation logistics advantages, not weather protection.
Mistake 2: Underestimating flood insurance as a standalone cost. Flood insurance ($1,500–$4,000/year) is mandatory and separate from windstorm insurance. Total annual insurance easily runs $8,000–$12,000 for oceanfront homes. Budget accordingly.
Mistake 3: Buying without confirming CRS status. Isle of Palms' CRS Class 5 rating saves $200–$1,000/year on flood insurance. Confirm your specific property qualifies before buying; some properties or policies may not.
Mistake 4: Thinking evacuation is "probably not necessary." Category 3+ hurricanes trigger mandatory evacuation island-wide. Plan for 1–2 evacuations per hurricane season as a routine cost of island ownership.
Mistake 5: Not inspecting pilings and foundation. Isle of Palms oceanfront homes are pilings; ground-level living doesn't exist. Piling inspection ($400–$600 annually) is not optional—pilings deteriorate and need replacement every 30–50 years. Factor into your long-term budget.
FAQ: Buying Luxury on Isle of Palms
Q: Is Isle of Palms safer than Sullivan's Island?
A: Flood risk is nearly identical (98% vs. 99%). The practical advantage is evacuation infrastructure—multiple routes and faster clearing times (3–6 hours vs. 8–14 hours). This is convenience, not safety.
Q: Should I buy oceanfront or interior Isle of Palms?
A: Interior homes ($600K–$1.5M) have lower insurance ($2,500–$4,000 windstorm), smaller windstorm deductibles (1% vs. 2%), and no piling maintenance. You sacrifice oceanfront views but gain substantial cost savings ($4,000–$6,000/year). Many discerning buyers choose interior for exactly this reason.
Q: How much can I save with CRS Class 5 rating?
A: Typically $200–$1,000/year on flood insurance depending on coverage amount and zone. Not transformational, but meaningful. Confirm your property qualifies before buying.
Q: What's the typical piling replacement cost?
A: Pilings last 30–50 years depending on wood type and maintenance. Replacement is $50,000–$150,000+ per home. This is a decades-out concern but factor it into long-term ownership costs.
Q: Do generators and impact windows reduce insurance?
A: Yes, by 5–10% on windstorm (~$300–$800/year). Payback period is 12–25 years. Real value is storm protection, not insurance savings.
Q: How often do I evacuate from Isle of Palms?
A: 1–2 times per hurricane season on average. Evacuation costs $2,000–$4,000 per event (hotels, logistics). Budget $2,000–$8,000/year for evacuation events + logistics.
Q: Can I get insurance quotes before buying?
A: Absolutely. Contact insurance agents specializing in coastal properties before making an offer. Use quotes to inform your offer strategy. If total insurance ($8,000–$12,000/year) exceeds your budget, adjust your offer or walk away.
Q: Is Isle of Palms a good second home location?
A: Yes, better than Sullivan's Island. Multiple evacuation routes allow remote management; you can close shutters, evacuate on your timeline, and return to-re-occupy faster. Better logistics for part-time ownership.
Q: What's the timeline for post-storm recovery?
A: Power typically restored 5–7 days (vs. 7–10 for Sullivan's Island due to better access); water 3–5 days; full debris removal 2–3 weeks. Plan for extended absence and cleanup costs.
Q: Should I buy a primary residence or second home on Isle of Palms?
A: Both work. Primary residence simplifies insurance and logistics. Second home benefits from better evacuation routing. Both face identical hurricane risk; choose based on your ownership model.
Final Answer
Isle of Palms offers barrier-island oceanfront access at more accessible price points than Sullivan's Island, with nearly identical hurricane and flood risk (98% vs. 99%) but notably better evacuation infrastructure. Annual insurance runs $8,000–$12,000 for oceanfront homes—less than Sullivan's Island but substantial compared to inland Charleston properties.
For luxury buyers seeking barrier-island oceanfront living without Sullivan's Island's ultra-premium costs and single-road evacuation bottleneck, Isle of Palms delivers pragmatism. The island's size, multiple evacuation routes, and broader price range appeal to established luxury buyers who want oceanfront access without exceptional risk-management complexity.
Flood insurance is mandatory and expensive. Budget $9,000–$12,000/year for insurance and $2,000–$4,000 for evacuation logistics. Understand that a $2M oceanfront Isle of Palms home costs roughly $300,000–$400,000 more over 20 years than a comparable Charleston peninsula property, mostly in insurance premiums.
Make this choice with eyes open, but for many luxury buyers, Isle of Palms represents an excellent balance between oceanfront prestige and practical affordability.
About Leah Beaulieu & BJ Rodgers — Coast2Coast Properties
Leah Beaulieu and BJ Rodgers are Charleston, South Carolina real estate professionals with Coast2Coast Properties, helping buyers compare neighborhoods, understand local market differences, and find the right fit across the Charleston area. Whether you are buying your first home, relocating to the Lowcountry, or looking for investment opportunities, Leah and BJ bring local knowledge, straight talk, and a genuine commitment to helping clients make smart decisions.
Coast2Coast Properties
www.coast2coastprop.com
843-697-1409 / 803-201-4259